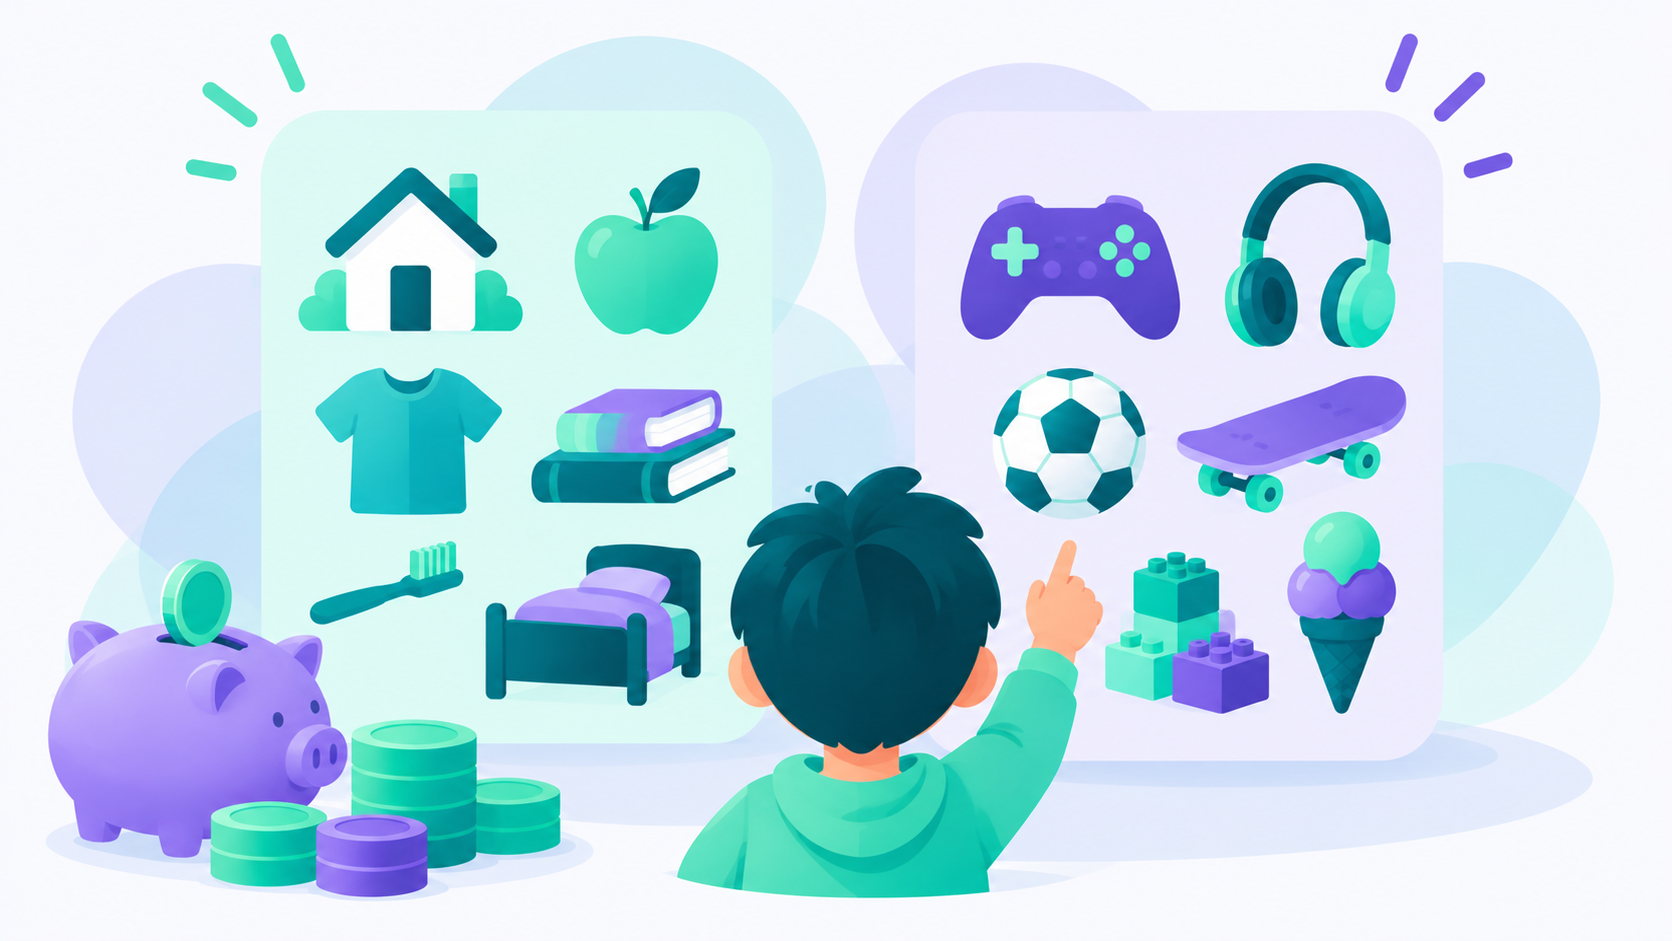
Teaching Kids the Difference Between Wants and Needs
Research from the University of Cambridge, commissioned by the UK’s Money Advice Service, found that children’s money habits are basically formed by age seven. Not starting to form. Formed. By the time most kids are in first or second grade, they’ve already developed emotional patterns and basic beliefs about money that they carry into adulthood.
That makes the wants versus needs conversation one of the most important financial lessons a parent can have with a child, and one of the earliest opportunities to shape how a kid thinks about money for the rest of their life.
Here’s how to have that conversation in ways that actually land, broken down by age, with specific activities that work in real life, not just in theory.
Why the Wants vs. Needs Distinction Matters
Before getting into tactics, it’s worth being clear on why this particular lesson carries so much weight.
The ability to distinguish between a genuine need and a perceived one is the foundation of almost every good financial decision a person makes. It underlies budgeting, it explains why some people save and others don’t, it’s what determines whether someone impulse-buys or thinks through a purchase. A child who can articulate the difference between wanting the latest sneakers and needing functional footwear has a cognitive tool they will use for the next sixty years.
As Pam Whalley, director of the Center of Economic and Financial Education at Western Washington University, put it: “If you do nothing else with your child than that, you’ve done more than most people.”
The challenge is that for children, the line can be genuinely blurry. A child who has worn the same shoes to school for two years while classmates wear new ones isn’t just being difficult when they say they need new shoes. Social belonging feels like a need at that age because in developmental terms, it partially is. Teaching this distinction requires acknowledging that complexity rather than dismissing it.
What Counts as a Need vs. a Want?
A need is something required for survival, safety, health, or basic functioning in daily life. Food, shelter, clothing sufficient to protect from the elements, access to education, and basic hygiene supplies are needs. A want is anything beyond that, things that improve comfort, enjoyment, or social experience, but that life continues without.
The tricky part is that the line shifts with context. A car is a want in a city with good public transit and a near-necessity in a rural area with no alternatives. A winter coat is a need in Minnesota in January. It’s a want in Southern California in the same month. Teaching kids about wants and needs means teaching them to think about context, not just to memorize a list.
A useful framing for younger kids is to ask three questions about anything they want: Can I live without it? Do I need it to be safe and healthy? Will something bad happen if I don’t have it? If the answers are yes, no, and no, it’s a want.
How to Teach Wants vs. Needs by Age
Ages 3 to 6: Keep it concrete and physical
Young children learn through observation and experience, not through explanation. At this age, the goal isn’t to explain the concept abstractly. It’s to name things correctly as you encounter them in daily life.
When you’re in the grocery store and your child asks for candy, say: “That’s a want. We don’t need it to be healthy, but it sounds delicious. We’re getting apples today because we need fruit.” When you’re buying shoes because the old ones are worn out: “These are a need. Your old ones don’t fit anymore and you need something on your feet for school.”
You’re not having a lesson. You’re labeling reality as it happens. That’s what sticks at this age.
Sorting activities work well too. Put pictures of everyday items in two piles, needs and wants, and let your child categorize them. A bed is a need. A new stuffed animal is a want. Pizza is food and food is a need, but pizza specifically is a want. Even the edge cases are useful teaching moments.
Ages 7 to 10: Introduce real money and real choices
By this age, children can understand that money is finite, that spending it on one thing means not having it for another, and that choices have trade-offs. This is the stage where allowances become a powerful teaching tool, not just pocket money.
Giving a child a regular allowance and a responsibility for certain purchases puts the concept of wants versus needs into practice in a way that no conversation can replicate. When the allowance is gone and there’s something they want, the lesson lands in a way that sticks. Better to make mistakes with $10 at age 8 than $100 at age 18.
Going through the family grocery list together and asking your child to identify which items are needs and which are extras is a practical exercise that reveals how budgeting works without requiring an abstract explanation. When you skip the name-brand cereal for the store brand, you can explain why: “We need cereal. We don’t need this specific kind.”
At this age, you can also start introducing the concept of delayed gratification for wants. If they want something that costs more than their weekly allowance, help them figure out how many weeks they’d need to save for it. Writing it down and tracking progress toward a goal makes saving feel concrete rather than abstract.
Ages 11 to 14: Add context and complexity
Older kids and early teens often blur the wants and needs line in a new way: social belonging. Peer pressure creates a category that feels like a need because fitting in with friends and feeling accepted is genuinely important at this developmental stage. Acknowledging that honestly, rather than dismissing it, makes the conversation more useful.
Try this: “I understand that having the same kind of phone your friends have feels really important, and the social part of that is real. What we’re working with is a budget, and in that budget, a phone is a want, even though I get why it doesn’t feel like one. Let’s talk about what we can do.”
This is also the age where you can start discussing advertising and marketing. Ads are designed to make wants feel like needs, and recognizing that mechanism is a genuinely useful life skill. Use commercials as discussion prompts. “What is that ad trying to make you feel? Is it making you think you need something?” Teaching kids to identify when they’re being influenced by marketing is a form of financial literacy that most adults never fully develop.
Ages 15 and up: Real budgets and real trade-offs
By high school, the conversation can become an actual planning exercise. If your teenager gets a part-time job, help them build a simple budget that distinguishes between what they need to cover (any personal expenses you’ve agreed they’re responsible for) and what they want to spend on. The act of planning it themselves, rather than receiving money and spending it freely, builds the habit that will matter when they’re managing rent and groceries on their own.
Reviewing expenses together, not as surveillance but as a collaborative analysis, helps teens see patterns in their own spending. “What percentage of your income went to wants last month? Does that feel right to you?” These questions develop self-awareness that persists into adulthood.
What to Do When Kids Push Back
Every parent has been in the grocery store checkout line with a child who is absolutely certain that the candy at eye level is a need. Here’s what actually works when that happens.
Acknowledge the want without caving to it. “That looks really good. That’s a want. We’re not getting it today.” Short, calm, clear, no lengthy explanation required. Children respond to consistency far more than to the quality of the argument you make.
Don’t say “we can’t afford it” when what you mean is “we’re choosing not to buy this.” Teaching kids that every spending decision is a choice, even when money is tight, gives them agency and builds financial thinking rather than anxiety. “We’re choosing to spend our grocery money on things we need” is more accurate and more empowering than “we can’t afford that.”
Use the moment when they’re calm, not when they’re upset. The middle of a meltdown in the cereal aisle is not the time for a lesson about delayed gratification. Talk about it later, at home, when things are calm and they can actually process the information.
How Your Own Habits Shape Theirs
Children learn more from watching than from being told. The University of Cambridge research noted that kids learn about money “from observation, instruction, and practice.” Observation comes first for a reason.
If you talk out loud about your own spending decisions, even briefly, children absorb that pattern. “I’m deciding not to get a coffee today because we already spent enough on food this week” is a real-time model of wants versus needs thinking that no worksheet replicates. You don’t need to narrate every purchase, just enough that kids see the decision-making process rather than only the outcome.
Your budget is the best teaching tool you have, even if you never show it to your kids directly. When you know what your household needs cost, what’s discretionary, and what you’re working toward, you can have confident, specific conversations with your children rather than vague ones.
A budgeting tool that lets you create unlimited custom categories makes this kind of clarity easier to maintain. Lucky Friday is a free budgeting app available on iOS and web that lets you build a category structure that matches how your family actually spends, with separate categories for groceries versus eating out, for school supplies versus entertainment, for fixed expenses versus discretionary ones. Core budgeting tools are free forever with no credit card required. Bank sync is available on the premium plan if you want transactions to import automatically, but the full budgeting capability is free.
Knowing your own numbers well enough to talk about them confidently with your kids is one of the most direct ways to give them a financial education. If you’re building those habits yourself and want a place to start, our post on building healthy money habits early in life walks through the foundation that makes these conversations possible.
Making It a Running Conversation, Not a One-Time Lesson
The most common mistake parents make with financial education is treating it as a single conversation to have once and check off the list. Research consistently shows that financial concepts develop through repeated exposure over time, not through a single memorable talk.
The wants versus needs distinction is best taught the way most real learning happens: gradually, repeatedly, in the context of real life. Every grocery run is an opportunity. Every birthday wish list is an opportunity. Every time your child sees an advertisement and asks if you can get whatever it’s selling, that’s an opportunity.
The goal isn’t to raise children who never want things. Wants are a normal and healthy part of human motivation. The goal is to raise children who can tell the difference, who can consciously decide when a want is worth pursuing and when it isn’t, and who understand that every spending decision is a choice with real trade-offs.
That skill, built early and reinforced consistently, is one of the most enduring gifts a parent can give. And according to the research, the window to build it is earlier than most people think.
Our post on small financial habits that create peace of mind is a good companion read if you’re thinking about how to extend these conversations into the habits that sustain financial wellbeing through adulthood.
Common Questions About Teaching Kids Wants vs. Needs
At what age should you start teaching kids about wants and needs?
You can start as early as age three or four with simple, concrete examples in daily life. Research from the University of Cambridge found that children’s money habits are largely formed by age seven, which means the years before school are more important for financial habit formation than most parents realize. You don’t need to have a formal lesson. Naming things correctly as wants or needs during everyday activities is enough to start building the framework.
What is the difference between wants and needs for kids?
A need is something required for safety, health, or basic daily functioning: food, shelter, appropriate clothing, education, and basic hygiene. A want is anything beyond that, things that improve comfort, enjoyment, or social life, but that aren’t essential to survival. The line can shift with context, which is part of what makes this a rich ongoing conversation rather than a single lesson.
How do you explain wants and needs to a five-year-old?
Keep it concrete and connected to things they can see and touch. Use sorting activities with pictures or real objects. Label things in real time during grocery shopping or errands. Ask simple questions: “Do we need this to be safe and healthy? Would something bad happen if we didn’t get it?” If the answers are no and no, it’s a want. Five-year-olds learn best through repetition and real-life examples, not through abstract explanation.
How do you teach older kids about wants vs. needs when peer pressure blurs the line?
Acknowledge the social dimension honestly rather than dismissing it. For teens, fitting in with peers is a genuine need at a developmental level, even when the specific item being requested is a want. Try separating the two: “I understand why this matters to you socially, and that’s real. In our budget, it’s still a want. Let’s figure out what we can do.” This approach validates their experience without caving to the request and keeps the conversation productive.
Does giving kids an allowance help them learn the difference between wants and needs?
Yes, significantly. An allowance puts the concept into practice in a way that no conversation can replicate. When children manage their own money, even a small amount, they experience firsthand what it means to have finite resources and make choices among competing wants. The mistakes they make with $10 at age eight are much cheaper than the same mistakes at age 28. Making the child responsible for certain purchases from their allowance accelerates the learning even further.
Sources
University of Cambridge via Money Advice Service. Children’s money habits are basically formed by age 7. Cited in CNBC, RoosterMoney, and Cambridge research. https://courses.homeword.com/?p=15862
Western Washington University. Director Pam Whalley on wants vs. needs as the single most important money lesson for children. https://news.wwu.edu/inthemedia/teach-kids-financial-skills-early-wwu-instructor-says
Greenlight. Wants vs. Needs: How to Teach Kids Healthier Money Habits. Age-appropriate activities and frameworks. https://greenlight.com/blog/wants-vs-needs
GoHenry. Explaining Needs vs. Wants to Your Child Without Overwhelming Them. https://www.gohenry.com/us/blog/financial-education/explaining-needs-vs-wants-to-your-child-without-overwhelming-them
RoosterMoney via CNBC. Average allowance by age and allowance habits among US families. 2018 survey of 10,000 users. https://courses.homeword.com/?p=15862
The Financial Express. Financial Literacy for Kids: Teaching the Distinction Between Needs and Wants. https://thefinancialexpress.com.bd/views/financial-literacy-for-kids-teaching-the-distinction-between-needs-and-wants
Retraite Quebec / Truth Lies and Work Podcast. Cambridge study on money habits formed by age 7 cited. February 2026. https://agents.truthliesandwork.com/segments/272-the-cambridge-study-money-habits-formed-by-age-7.md